
This article is part of our complete guide to income tax in India. Before you invest for this deduction, check that the old regime is cheaper for you with the old vs new tax regime calculator.
The Short Answer
Section 80C is now section 123 of the Income-tax Act, 2025. Nothing about it changed except the number: you can still deduct up to ₹1.5 lakh a year for a list of investments and payments, including EPF, PPF, ELSS, life insurance premium, home loan principal and children’s tuition fees. It is available only in the old tax regime.
Two things decide whether it is worth anything to you. First, which regime you are in: in the new regime, section 123 saves nothing. Second, how much of the ₹1.5 lakh you have already used without trying: EPF, a home loan and school fees often fill it before you invest a rupee.
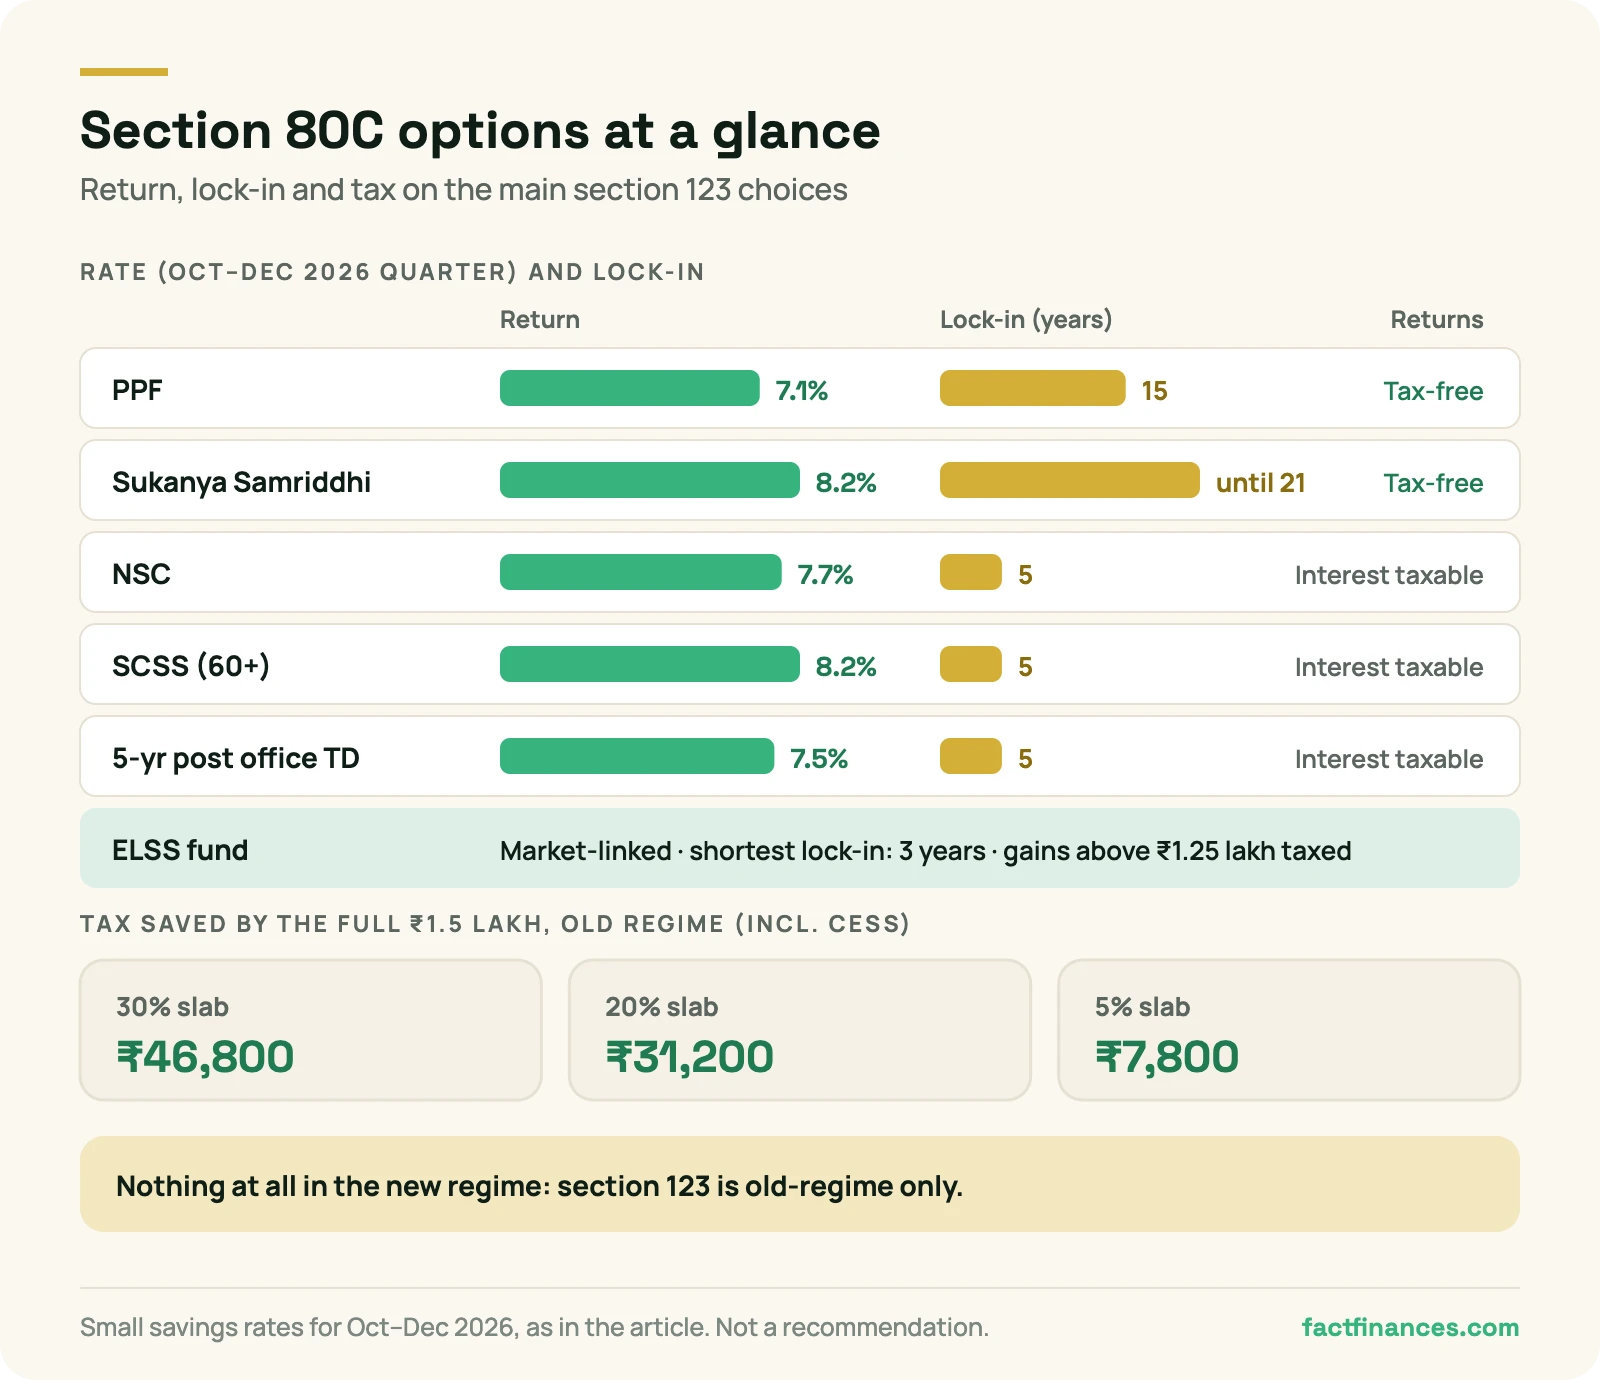
At the 30% slab, a full ₹1.5 lakh deduction saves ₹46,800 including cess; at 20%, ₹31,200; at 5%, ₹7,800.
What Qualifies
What counts under section 80C (now section 123)
The eligible items are listed in Schedule XV of the new Act. They fall into three groups:
| Group | Items |
|---|---|
| Things you may already be paying | Your own EPF contribution (not the employer’s); home loan principal on a residential house; stamp duty and registration on buying one (in the year paid); tuition fees for up to two children in full-time education in India; life insurance premiums for you, your spouse and children |
| Small savings and deposits | PPF; Sukanya Samriddhi; NSC; Senior Citizens Savings Scheme; 5-year tax-saver bank FD or post office time deposit |
| Market-linked and pension products | ELSS mutual funds; ULIPs; your own contribution to NPS Tier I; deferred annuity and pension plans (the old 80CCC) |
One cap for all of them. The ₹1.5 lakh is a single limit across every item, including the pension-plan premium and your own NPS contribution. Paying ₹80,000 into EPF and ₹1 lakh into PPF still gets you ₹1.5 lakh, not ₹1.8 lakh. Separately, NPS allows up to ₹50,000 more on top (the old 80CCD(1B)), also only in the old regime.
Check First
You may have used it up already
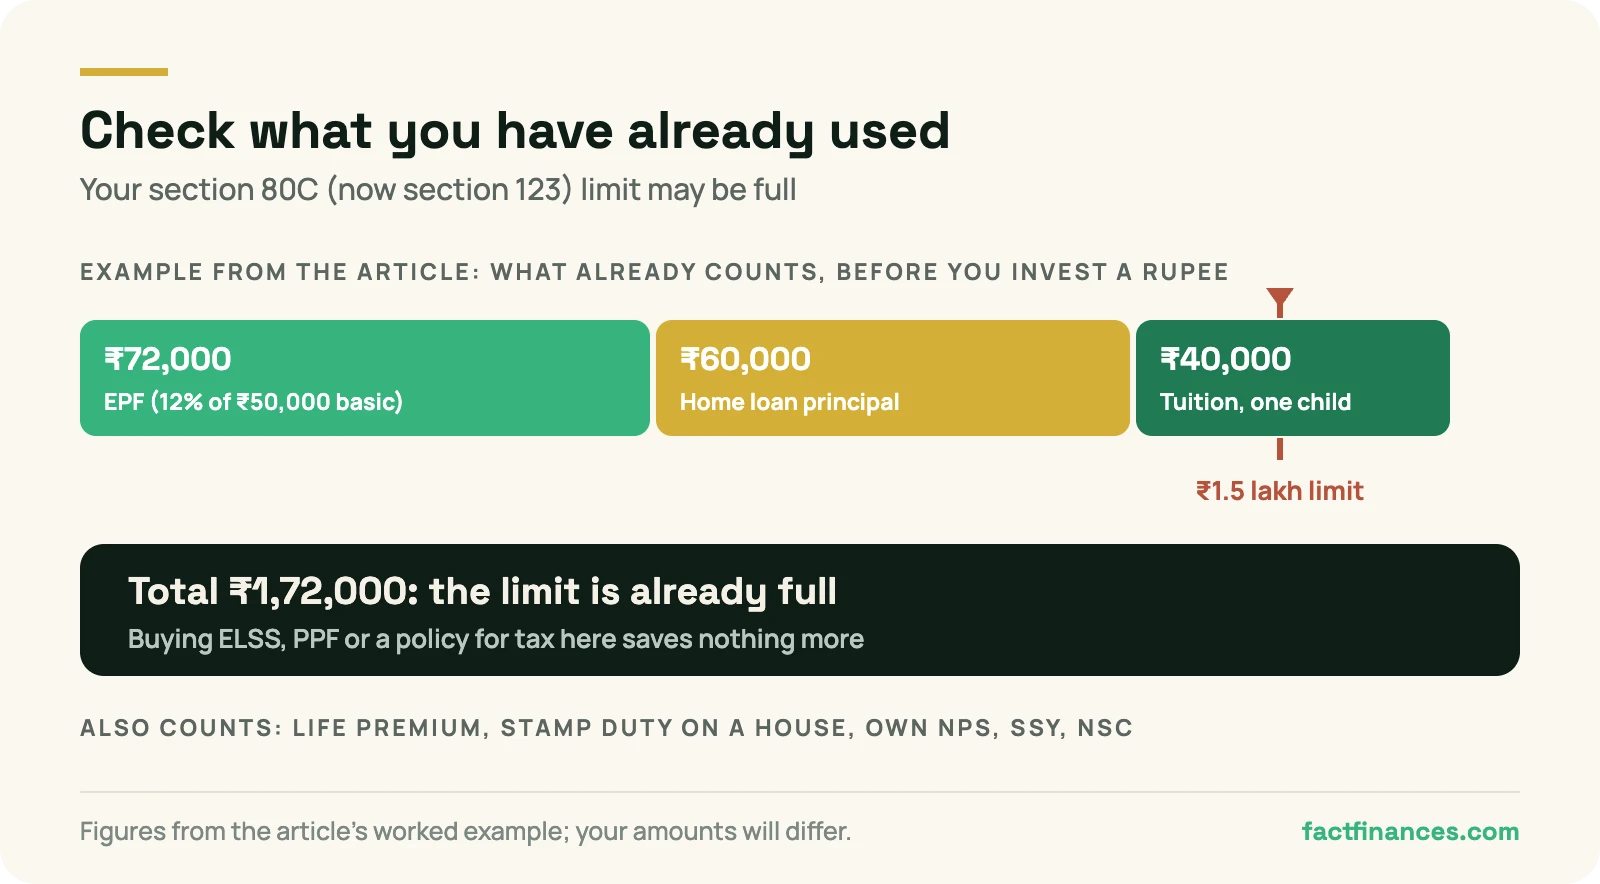
Before you buy anything for tax, add up what already counts. A typical salaried example:
| Item | Amount for the year |
|---|---|
| Your EPF (12% of ₹50,000 basic a month) | ₹72,000 |
| Home loan principal | ₹60,000 |
| School tuition fee, one child | ₹40,000 |
| Total | ₹1,72,000, already over ₹1.5 lakh |
This person needs to invest nothing more under section 123. Any ELSS or PPF they add is for its own sake, not for tax. Your payslip, loan statement and fee receipts tell you where you stand.
The Options Compared
Section 123 options side by side
Rates are for October to December 2026. Small savings rates are reset every quarter.
| Option | Return | Lock-in | Tax on the returns | Risk |
|---|---|---|---|---|
| ELSS mutual fund | Market-linked | 3 years (shortest) | Long-term gains above ₹1.25 lakh a year taxed at 12.5% | Equity market risk |
| PPF | 7.1% | 15 years (partial withdrawal from year 7) | Tax-free | Government-backed |
| Sukanya Samriddhi (girl child under 10) | 8.2% | Until the girl turns 21 (partial at 18) | Tax-free | Government-backed |
| NSC | 7.7% | 5 years | Interest taxable (reinvested interest counts for 123) | Government-backed |
| Senior Citizens Savings Scheme (60+) | 8.2% | 5 years | Interest taxable | Government-backed |
| 5-year post office time deposit | 7.5% | 5 years | Interest taxable | Government-backed |
| 5-year tax-saver bank FD | Bank’s rate | 5 years | Interest taxable | Bank deposit |
| NPS Tier I (own contribution) | Market-linked | Until 60, mostly | Partly tax-free at exit; part must buy an annuity (PFRDA rules) | Mixed, by allocation |
| Life insurance / ULIP premium | Depends on plan | Policy term; ULIP 5 years | Maturity tax-free only within premium limits | Plan-specific |
PPF and Sukanya Samriddhi interest stays tax-free in both regimes, so they remain useful even if you move to the new regime and lose the deduction.
Rules and Catches
Conditions that catch people out
- Life insurance premium counts only up to 10% of the sum assured for policies issued after 1 April 2012 (15% for policies on people with specified disabilities or diseases). A policy with a small cover and a big premium gets only part of the deduction.
- Stopping early reverses the deduction. If you stop a regular life policy within two years, or a ULIP within five, the deductions you claimed are added back to your income that year.
- Selling the house within five years of getting possession reverses the home loan principal deductions claimed.
- Tuition fees mean tuition only, for up to two children, in full-time education in India. Development fees, donations, transport and coaching classes do not count.
- Timing: the deduction is for the year you pay. An ELSS bought on 2 April falls into the next year.
Is It Worth It?
Section 80C, section 123 and the regime choice
Section 123 matters only if the old regime is cheaper for you overall. For most salaried people that needs HRA or a home loan on top: at ₹15 lakh, the old regime needs about ₹5.4 lakh of deductions to win, and section 123 can supply at most ₹1.5 lakh of it.
So the order of decisions is: first, check the regime with the regime calculator (and our guide to choosing a regime); second, add up what you already pay that counts; third, if there is a gap and the old regime wins, fill it with something you would want to own anyway.
If you rent, your HRA exemption is usually the bigger lever.
Common Mistakes
Mistakes people make with section 80C and section 123
1. Buying insurance to save tax
A savings-type policy bought in March for the deduction often returns less than a PPF after charges, and stopping it early reverses the tax benefit. Buy cover for protection, and size it properly.
2. Investing for tax in the new regime
If you file under the new regime, section 123 investments give you no deduction at all.
3. Forgetting what already counts
EPF, home loan principal and tuition fees often fill most of the ₹1.5 lakh.
4. Counting the employer’s EPF share
Only your own contribution counts. The employer’s share is separately exempt within limits.
5. Locking money you will need
PPF locks for 15 years and Sukanya Samriddhi until 21. Match the lock-in to the goal, not to the tax deadline.
Talk It Through
Not sure whether to invest for tax this year?
Tell us your salary, regime, EPF, loans and any investments you already have. We will work out whether section 123 saves you anything, how much room is left, and help you file your ITR. Ranchi, Deoghar and across India online.
Chat on WhatsApp Send a message · Old vs new regime calculator
Key takeaways
→ Section 80C is now section 123, with the same ₹1.5 lakh limit and the same eligible items. Old regime only.
→ EPF, home loan principal, tuition fees and life premium all count. Add them up before investing.
→ At the 30% slab a full ₹1.5 lakh saves ₹46,800; at 20%, ₹31,200.
→ ELSS has the shortest lock-in (3 years); PPF and Sukanya Samriddhi are tax-free in both regimes.
→ Stopping a policy early or selling the house within five years reverses the deduction.
Questions
Frequently asked questions
Is section 80C still available?
Yes, as section 123 of the Income-tax Act, 2025, from FY 2026-27. The ₹1.5 lakh limit and the eligible investments are unchanged. It is available only in the old tax regime.
What is the maximum deduction under section 123?
₹1.5 lakh a year in total across all eligible items, including pension plan premium and your own NPS contribution. NPS allows up to ₹50,000 more on top, also in the old regime only.
Can I claim 80C or section 123 in the new tax regime?
No. The new regime does not allow it. You can still invest in PPF, ELSS and the rest, but you get no deduction.
Does EPF count towards section 123?
Your own contribution does, including voluntary PF. Your employer’s contribution does not count.
Which section 123 investment has the shortest lock-in?
ELSS mutual funds, at three years from each investment. Tax-saver FDs, NSC and SCSS lock for five years, PPF for fifteen.
Do school fees count?
Tuition fees do, for up to two children in full-time education in India. Development fees, donations and transport charges do not.
Keep Learning
Next steps: Old vs new regime calculator · HRA exemption · Section 80D: health insurance deduction
The bigger picture: The complete guide to income tax in India · What the Income-tax Act, 2025 changed
About the author
Ujjwal Tiwary
ARN-144500 · NISM Series V-A certified since 2018 · Ranchi & Deoghar, Jharkhand
Ujjwal Tiwary is an AMFI-registered mutual fund distributor (ARN-144500) based in Ranchi and Deoghar, Jharkhand, and has held the NISM Series V-A certification since 2018. He works with families on mutual funds, insurance and income tax returns, and writes or personally reviews every article on FactFinances. He is not a SEBI-registered investment adviser; nothing on this site is personalised advice.
Disclaimer: FactFinances provides educational content only. This article is general information and is not tax, legal or financial advice. It is based on the Income-tax Act, 1961 (which still governs returns for FY 2025-26 and earlier) and the Income-tax Act, 2025 (in force from 1 April 2026), as understood at the time of writing. Tax law, due dates and their interpretation can change, and your tax depends on your full facts; check the current position on the Income Tax Department portal or consult a chartered accountant before acting. FactFinances offers ITR filing assistance; reading this article places you under no obligation to use it.