
This article is part of our complete guide to insurance in India. It’s the third in the family of policies that bundle investing into life cover, after endowment and guaranteed-return plans — but with one big difference: the returns here ride the market.
Tax law update (October 2026). The Income-tax Act, 2025 replaced the Income-tax Act, 1961 from 1 April 2026, renumbering most sections. Other provisions cited here, such as Section 10(10D), have also been renumbered. We use the familiar old section numbers below because that is how most people still search for them. Returns for FY 2025-26 are still filed under the 1961 Act.
The Core Idea
A ULIP — Unit-Linked Insurance Plan — is the third member of India’s “insurance plus investment” family, sitting alongside endowment and guaranteed-return plans. All three bundle life cover with a savings element. What sets the ULIP apart is one crucial twist: its investment portion is market-linked, not fixed. Your money buys units in funds of your choice, the value rises and falls with the markets, and you carry both the risk and the upside — much like a mutual fund wrapped inside an insurance policy.
That hybrid nature is exactly why ULIPs confuse people. They’re sold as insurance, behave partly like investments, come layered with charges, and carry their own tax rules. This article breaks the ULIP down to its parts: what it actually is, where every rupee of your premium goes, the charges that quietly shape your real return, the tax rules after the 2021 change, and the specific buyer a ULIP genuinely fits. This is education, not a recommendation — the aim is to let you read a ULIP clearly before anyone pitches one to you.
A ULIP is a mutual-fund-style investment and a life cover, stitched into one policy — with charges and a lock-in that the two separately wouldn’t carry.
What It Is
What a ULIP actually is
A ULIP is a life insurance policy where your premium is split into two jobs. A portion pays for life cover, so your family receives a payout if you die during the term. The rest is invested in market-linked funds — equity, debt, or balanced — that you choose, and you’re allotted “units” in those funds at the prevailing net asset value (NAV), exactly like a mutual fund. As the funds rise or fall, so does the value of your policy.
Two features define the ULIP wrapper. First, a mandatory five-year lock-in — you cannot withdraw the money in the first five years, even though insurance cover continues. Second, the ability to switch between funds within the policy (say, moving from equity to debt as you near a goal) without it being treated as a sale. Both features matter later when we look at who a ULIP suits.
Where Your Money Goes
How a ULIP works: where your premium goes
When you pay a ULIP premium, it doesn’t all go into your funds. It’s divided several ways before the remainder is invested. A slice pays the mortality charge — the genuine cost of your life cover. Other slices cover the insurer’s administration and fund-management charges, and in some plans a premium allocation charge taken upfront. Only what’s left after these deductions actually buys units in your chosen funds.
This is the single most important thing to understand about a ULIP: your real return is whatever the funds earn minus the stack of charges. In the early years especially, charges can take a meaningful bite, which is why ULIPs reward long holding periods where the charges thin out relative to a growing corpus. The good news is that since IRDAI tightened the rules in 2010, ULIP charges are capped and far lower than the notoriously expensive products of the 2000s — but they still exist, and they still matter.
Two Numbers, Two Jobs
Sum assured vs fund value: the two numbers in every ULIP
Every ULIP statement shows two numbers that buyers routinely confuse. The sum assured is your life cover: an amount fixed when you buy the policy. The fund value is what your units are worth today (units held × NAV). It moves every day with the markets and is reduced by every charge.
| Sum assured | Fund value | |
|---|---|---|
| What it is | The life cover written into the policy | The current market value of your units |
| Who sets it | You, at purchase, as a multiple of the annual premium | The markets, minus charges |
| Does it change? | Fixed, unless you change the cover | Daily, with the NAV |
| At maturity | Not paid | Paid: it is your maturity value |
| Link to tax | Annual premium must stay within 10% of it for tax-free maturity | Taxed as capital gains only if the premium conditions fail |
What your family receives on death
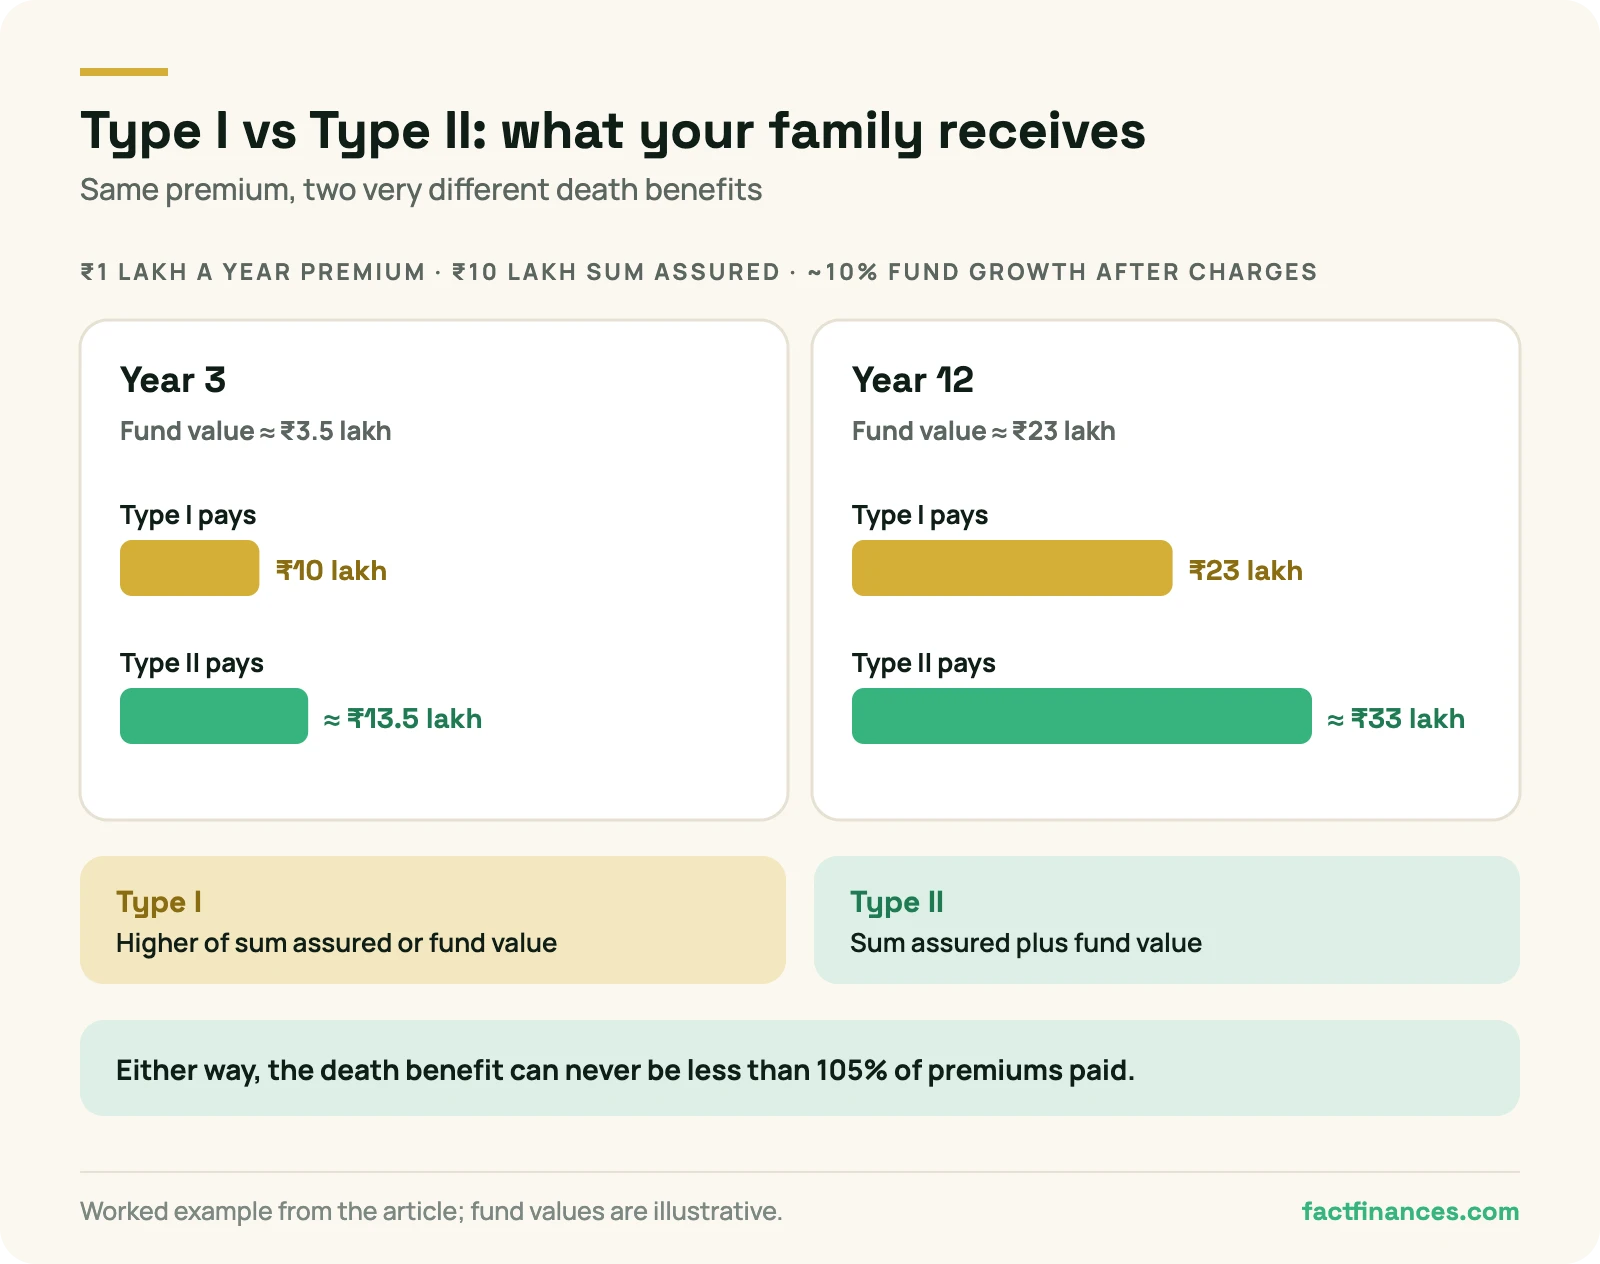
This depends on the plan type, and it is worth checking before you buy. Most ULIPs pay the higher of the sum assured and the fund value (often called Type I). Some pay both, the sum assured plus the fund value (Type II). Type II costs more, because the insurer’s risk never shrinks. Either way, the death benefit cannot be less than 105% of the premiums you have paid.
An example. You pay ₹1 lakh a year with a sum assured of ₹10 lakh, and the fund grows at about 10% a year after charges. In year 3 the fund value is about ₹3.5 lakh, so a Type I policy pays ₹10 lakh on death and a Type II policy about ₹13.5 lakh. By year 12 the fund value is about ₹23 lakh. Type I now pays ₹23 lakh, which is simply your own money, because the fund has overtaken the cover. Type II pays about ₹33 lakh.
Why this matters: in a Type I ULIP, the mortality charge is levied on the sum at risk (sum assured minus fund value). As your fund grows, the real insurance inside the policy shrinks towards zero. That is efficient for an investment, but it means a ULIP’s cover is not a plan for protecting your family. A separate term plan is.
The Charges
The charges that decide your real return
Because charges are deducted before and during investment, knowing the main types lets you read any ULIP illustration with clear eyes. These are the usual ones:
| Charge | What it pays for | What to expect |
|---|---|---|
| Premium allocation | Taken from each premium before it is invested | Often 0% in online plans; in offline plans it varies by plan and policy year, mostly in the early years — IRDAI caps it at 12.5% of the premium in any year |
| Mortality | The cost of your life cover, charged on the sum at risk | Deducted monthly by cancelling units; rises with age |
| Fund management (FMC) | Managing your chosen funds | IRDAI caps it at 1.35% a year. A direct equity mutual fund typically costs about 0.5–1%, an index fund about 0.1–0.3% |
| Policy administration | Running the policy | A monthly deduction, often ₹50–100 |
| Discontinuance | Stopping or surrendering in the first five years | Capped by regulation; the money moves to a discontinued policy fund until year five |
| Switching | Moving between funds | Usually a few free switches a year; a small fee beyond them |
Three details the table cannot show. Before IRDAI’s 2010 reforms, many ULIPs took 20–30% of early premiums as allocation charges, which is where the category’s bad reputation comes from. The mortality charge rises every year as you age, and over a 20-year policy with a large sum assured the cumulative total can run into lakhs. And if you stop paying within the first five years, your money moves to a discontinued policy fund that earns a modest regulated return (a minimum of 4% a year) until the lock-in ends, after deducting a capped discontinuance charge.
Some modern ULIPs market themselves as “zero allocation charge” or even add back certain charges as loyalty units over time. That can genuinely improve the long-run return — but it’s exactly the kind of claim to verify in the benefit illustration rather than take on trust. Always ask to see the net, post-charge return projection, not just the gross fund performance.
One number that sums up every charge: reduction in yield
IRDAI requires every ULIP benefit illustration to show the reduction in yield: how much all the charges together cut your annual return. If the fund earns 10% and the reduction in yield is 1.5%, you keep 8.5%. Over 20 years that gap is worth lakhs. Ask for this figure before you sign, and compare it with the expense ratio of a mutual fund doing the same job.
The Tax Angle
ULIP taxation: the ₹2.5 lakh rule
ULIPs once enjoyed fully tax-free maturity proceeds, which was a large part of their appeal. The Finance Act 2021 changed that for high-premium policies. Under the current rules, for ULIPs issued on or after 1 February 2021, the maturity proceeds are tax-free under Section 10(10D) only if the aggregate annual premium across all your ULIPs stays at ₹2.5 lakh or less. Cross that ceiling and the gains are treated as capital gains and taxed accordingly.
A couple of points complete the picture. The long-standing condition that the annual premium not exceed 10% of the sum assured also applies for the maturity to qualify as tax-free. And as with every life policy, the death benefit is always tax-free, regardless of premium size. For most ordinary buyers paying modest premiums, ULIP maturity remains tax-free; it’s the large-premium buyers who lost the old advantage. Tax rules change and depend on your circumstances, so confirm the current position with a qualified tax professional.

Where It Fits
Who a ULIP suits — and who it doesn’t
A ULIP is neither a scam nor a silver bullet — it’s a specific tool with real strengths and real limitations. It can suit:
- Someone who genuinely wants insurance and market investing in one wrapper and values the simplicity of a single product over managing two.
- A long-horizon investor (well beyond the five-year lock-in) who will stay invested long enough for charges to thin out and compounding to work.
- Those who value tax-free fund switching — moving between equity and debt inside the policy isn’t a taxable event, whereas switching funds outside a ULIP can trigger capital gains. For an active asset-allocator within the ₹2.5 lakh limit, that’s a real edge.
It fits poorly in two common situations. If your real need is protection, the life cover in a ULIP is usually modest for the premium, leaving a wide protection gap that a cheap term plan would close far better. And if your goal is simply the lowest-cost, most flexible market exposure, direct mutual funds typically win on cost and liquidity. That head-to-head deserves its own article — we run the full comparison in ULIP vs mutual funds. As with the rest of this family, the cleanest default for most people is to separate the jobs: protect with term, invest where it’s cheapest and most flexible.
The Honest Three-Part Assessment
Case for, case against, our standing framework
The case for: post-2010 online ULIPs with zero allocation charges and FMC near 1% are meaningfully cheaper than their ancestors. The 10(10D) tax shelter within ₹2.5L is real and valuable for high-bracket investors. Fund switches are tax-free. The five-year lock-in, for undisciplined investors, functions as forced good behaviour — an underrated feature for someone who would otherwise churn their equity portfolio in every market dip. And the life cover, however modest relative to a term plan, is built in at no separate application process.
The case against: the fusion means neither part is optimal. The life cover is typically far too small to protect a family — a ₹1.5 lakh annual premium might buy ₹15 lakh of cover, a fraction of genuine need. The investment component still carries mortality and administration charges a mutual fund doesn’t. Liquidity is poor for five years, and the surrender charge structure is unkind to anyone who changes their mind early. And the product’s commission structure — while regulated — has historically made it the most mis-sold instrument in Indian retail finance, sold as “investment with free insurance” to people who needed either real insurance or a clean investment, and got neither properly.
Our standing framework: insurance and investment usually work better separated — a term plan for protection plus mutual funds for growth typically beats a ULIP on both dimensions, and the comparison is clearest when you run actual numbers. The narrow lane where a ULIP genuinely competes: a disciplined high-bracket investor who has already bought adequate term cover, maxes the 10(10D) window deliberately, holds the full term without needing the money, and picks a low-charge online ULIP with eyes open. Outside that lane, separate the jobs.
Our Brand Position On ULIPs
Why we keep ULIP content education-only
ULIPs are the most mis-sold product in Indian retail finance — not because every seller is dishonest, but because the commission structure has historically been rich and front-loaded, creating an incentive to sell ULIPs to people who would be better served by a term plan plus mutual funds. An anti-hype brand recommending ULIPs without full disclosure would be a credibility contradiction.
So across FactFinances, all ULIP content stays education-only: we explain honestly, we run the numbers transparently, and we route readers to the right tools and the full comparison. We do not solicit ULIPs even though our IRDAI agency credentials would technically permit it. If after reading the full comparison you decide a ULIP fits your situation, you should buy it from a licensed IRDAI-registered advisor who can provide a personalised benefit illustration from the insurer directly — and who discloses their commission. We’ve provided the framework; the product decision is yours.
Before You Buy
Three things to check before buying a ULIP
If a ULIP is being recommended to you, three checks will tell you whether it’s a fit or just a sale.
- Look at the net, post-charge return — not the gross. Benefit illustrations show fund growth at assumed rates; ask specifically for the value after all charges are deducted. That’s the number that ends up in your hands.
- Check the life cover against your actual need. If the bundled sum assured is far below what your family would require, the ULIP isn’t solving your protection problem — and you may need a separate term plan regardless.
- Match the horizon to the lock-in and your premium to the ₹2.5 lakh line. Be honest about whether you’ll stay invested for the long term the product assumes, and where your total ULIP premiums sit relative to the tax threshold.
If those three stack up for your situation, a ULIP may genuinely suit you. If they don’t, separating protection and investment will almost always serve you better.
Key takeaways
• A ULIP bundles life cover with market-linked investing in one policy. You choose the funds, and you carry both the risk and the upside — unlike fixed endowment or guaranteed plans.
• Your premium is split between life cover, several charges, and the units actually bought. Your real return is fund performance minus charges — so always ask for the net, post-charge projection.
• ULIPs carry a five-year lock-in. Charges are IRDAI-capped and far lower than pre-2010, but still reward long holding periods.
• Maturity is tax-free only if aggregate annual ULIP premium is ₹2.5 lakh or under (policies issued on/after 1 Feb 2021); above that, gains are taxed as capital gains. Death benefit is always tax-free.
• The sum assured is your cover; the fund value is your money. On death most ULIPs pay the higher of the two, so the insurance inside shrinks as the fund grows.
Frequently asked questions
What is a ULIP in simple terms?
A ULIP is a life insurance policy that also invests your money in market-linked funds. Part of your premium buys life cover; the rest buys units in equity, debt, or balanced funds you choose, and the value moves with the markets. It’s essentially insurance and a mutual-fund-style investment combined into a single product, with its own charges and a five-year lock-in.
Is a ULIP a good investment?
It depends on your goal. For someone wanting insurance and market investing in one long-term wrapper, with tax-free fund switching within limits, a ULIP can work. But for pure protection it offers too little cover for the cost, and for the cheapest, most flexible market exposure, direct mutual funds usually win. Match the tool to the job rather than treating it as universally good or bad.
What is the lock-in period for a ULIP?
Five years. You cannot withdraw your money during this period, although your life cover continues throughout. Because charges weigh more heavily in the early years, ULIPs are generally suited to horizons well beyond the minimum five-year lock-in.
Are ULIP returns guaranteed?
No. Unlike endowment or guaranteed-return plans, a ULIP’s returns depend entirely on how the market-linked funds you choose perform. You can earn more than a fixed plan over the long run, but you also bear the risk of market falls. There is no guaranteed maturity value on the investment portion.
Is ULIP maturity tax-free?
For ULIPs issued on or after 1 February 2021, maturity is tax-free under Section 10(10D) only if your aggregate annual premium across all ULIPs is ₹2.5 lakh or less (and within 10% of the sum assured). Above that limit, the gains are taxed as capital gains. The death benefit is always tax-free. Confirm the current rules with a tax professional, as tax law can change.
Is the sum assured the same as the fund value in a ULIP?
No. The sum assured is the life cover fixed in the policy; the fund value is the current market value of your units. At maturity you receive the fund value. On death, most ULIPs pay the higher of the two (Type I), while some pay both (Type II). The death benefit is never less than 105% of premiums paid.
My ULIP has completed five years and is underwater. Exit or hold?
After year five there is no discontinuance charge, so leaving costs less. Weigh three things: the charges you will keep paying (fund management and mortality) against a lower-cost alternative, whether you still need the cover (if you do, buy term first), and the tax position of the proceeds. Losses are not recovered by staying in a product; they are recovered by the market, and that can happen in a cheaper wrapper. A tax professional can confirm the treatment of surrender proceeds for your policy.
What is reduction in yield in a ULIP?
It is the total drag of all charges on your annual return, shown in the benefit illustration. A fund earning 10% with a 1.5% reduction in yield leaves you 8.5%. It is the single best number for comparing ULIPs with each other and with mutual funds.
Is a ULIP an investment or insurance?
Legally insurance (regulated by IRDAI), economically mostly investment (the bulk of the premium buys units in a market-linked fund), practically both. The mortality charge is the insurance cost embedded in the product. Judge it primarily as an investment that includes a small insurance cost, because that’s how the rupees actually flow — the life cover alone rarely justifies the product.
Why do sellers push ULIPs so hard?
Commission structures on insurance products have historically been richer and more front-loaded than on mutual funds. That’s not an accusation against any individual seller — it’s a structural fact about incentives, and it’s exactly why our house rule is to keep all ULIP content education-only and disclose distribution economics openly. An honest seller will show you the commission they earn on the recommendation and compare the ULIP against a term-plus-MF alternative before recommending either.
Keep Learning
Next steps: ULIP vs mutual funds · Guaranteed-return plans · Term vs endowment · Insurance policy IRR calculator · Human life value calculator
The bigger picture: The complete guide to insurance in India · The complete guide to mutual funds in India
Free · Printable · 10 minutes
Your 5-point money check-up
A 10-minute printable that shows where your family’s money is protected and where it isn’t. Plus one useful money article a month. No spam.
General information only, not personalised advice. Ujjwal Tiwary, AMFI-registered Mutual Fund Distributor, ARN-144500.
About the author
Ujjwal Tiwary
ARN-144500 · NISM Series V-A certified since 2018 · Ranchi & Deoghar, Jharkhand
Ujjwal Tiwary is an AMFI-registered mutual fund distributor (ARN-144500) based in Ranchi and Deoghar, Jharkhand, and has held the NISM Series V-A certification since 2018. He works with families on mutual funds, insurance and income tax returns, and writes or personally reviews every article on FactFinances. He is not a SEBI-registered investment adviser; nothing on this site is personalised advice.
Disclaimer: FactFinances provides educational content only. This article is for general information and is not insurance, investment, or tax advice, and does not recommend any specific product, plan, or insurer. Insurance is the subject matter of solicitation. Market-linked investments carry risk, including loss of capital; ULIP returns depend on fund performance and are not guaranteed. Charges and tax treatment vary by plan and depend on current law and individual circumstances and may change; the ₹2.5 lakh ULIP threshold reflects rules introduced by the Finance Act 2021. Please verify the current position with a qualified tax professional, read all policy documents carefully, and consult a licensed advisor before making any decision. ARN-144500. Regulatory information: IRDAI.