
This article is part of our complete guide to income tax in India. For the full capital gains rules, see capital gains tax on every asset.
The Short Answer
Tax harvesting means selling equity shares or equity mutual fund units you have held for more than a year, booking up to ₹1.25 lakh of long-term gain, and buying them straight back. The gain is tax-free because it falls inside the yearly exemption, and your purchase cost resets higher, so less of your future gain will be taxed.
The exemption is ₹1.25 lakh per person per financial year. It cannot be carried forward: if you do not use it by 31 March, that year’s exemption is gone. Booking ₹1.25 lakh every year saves up to ₹16,250 a year (12.5% plus cess) when you eventually sell.
For FY 2026-27, the sale must happen by 31 March 2027. Aim for the first half of March, because funds take a few working days to process and the market is shut on some days near the year end.
How It Works
How tax harvesting saves tax
Long-term gains on listed shares and equity funds are taxed at 12.5%, but only above ₹1.25 lakh a year. Most long-term investors never sell in most years, so the exemption lapses unused. Harvesting uses it every year.
Example
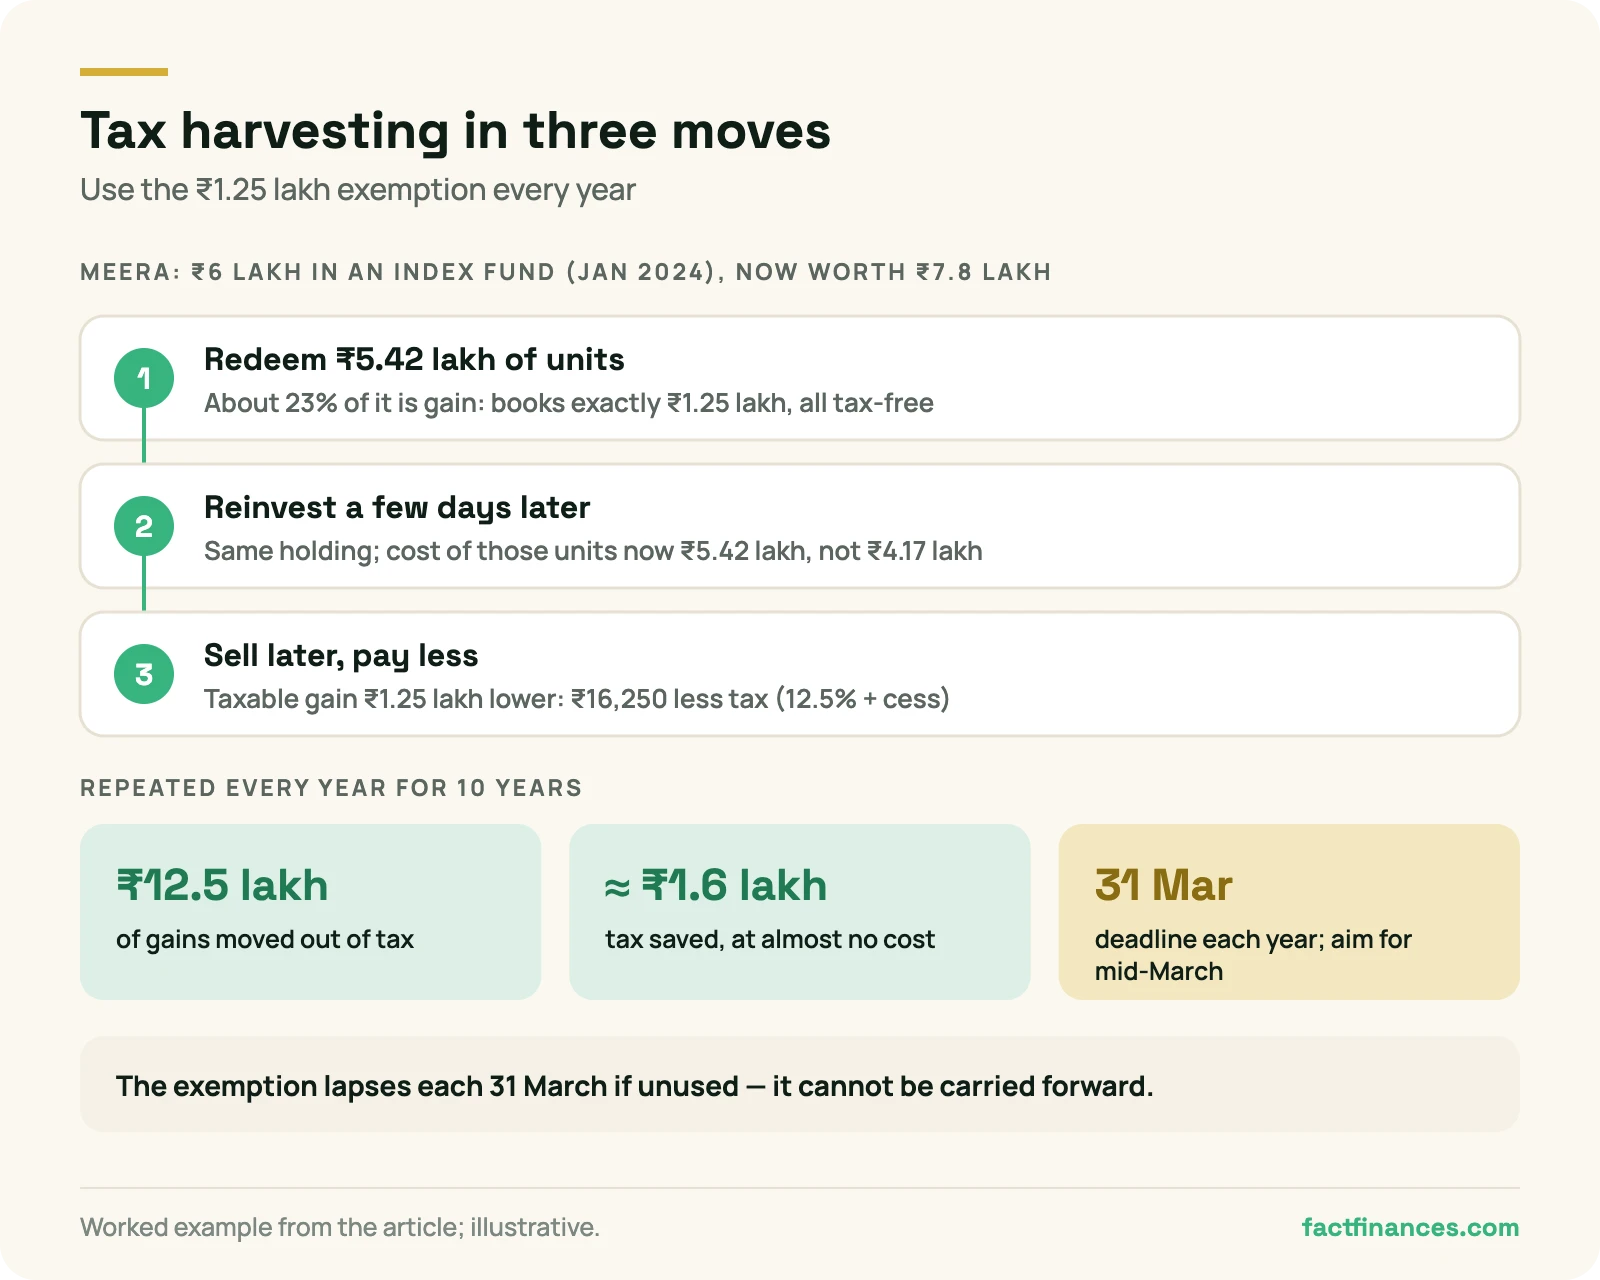
Meera put ₹6 lakh into an equity index fund in January 2024. It is now worth ₹7.8 lakh, a gain of ₹1.8 lakh, and she has no other gains this year.
- She redeems ₹5.42 lakh of units. About 23% of their value is gain, so this books ₹1.25 lakh of long-term gain, all of it exempt.
- She reinvests the ₹5.42 lakh in the same fund a few days later. Her holding is unchanged, but the cost of those units is now ₹5.42 lakh instead of ₹4.17 lakh.
- When she finally sells, her taxable gain is ₹1.25 lakh lower, which saves ₹16,250 of tax at 12.5% plus cess.
Repeated every year for ten years, that is ₹12.5 lakh of gains moved out of tax, and about ₹1.6 lakh of tax saved, at almost no cost.
This is a real saving, not a delay. Each year’s exemption that goes unused is lost for good, so tax you avoid by harvesting is never paid later. Even heirs benefit: inherited units keep your cost, so a higher cost means less tax when they sell.
Step by Step
How to harvest gains before 31 March
- Check your gains so far this year. Add up long-term gains already booked on listed shares, equity funds and REIT or InvIT units in FY 2026-27. Only the unused part of ₹1.25 lakh is available.
- Find units held more than 12 months. Your broker’s or CAMS/KFintech’s capital gains statement shows unrealised gains lot by lot.
- Work out how much to sell. Sell enough to book the gain you want, not the whole holding. Leave a margin of a few thousand rupees for price moves on the day.
- Sell, then buy back. For shares, buy back on the next trading day, not the same day. For funds, reinvest once the redemption money arrives.
- Keep the statements. Report the sale in your return; the AIS will show it anyway.
Units are sold oldest first
Both funds and demat shares are sold on a first-in, first-out basis. With a SIP, your oldest instalments go first, and they usually have the largest gains, so a small redemption may book more gain than you expect. Check the lot-wise statement before you sell.
Do not buy back shares on the same day
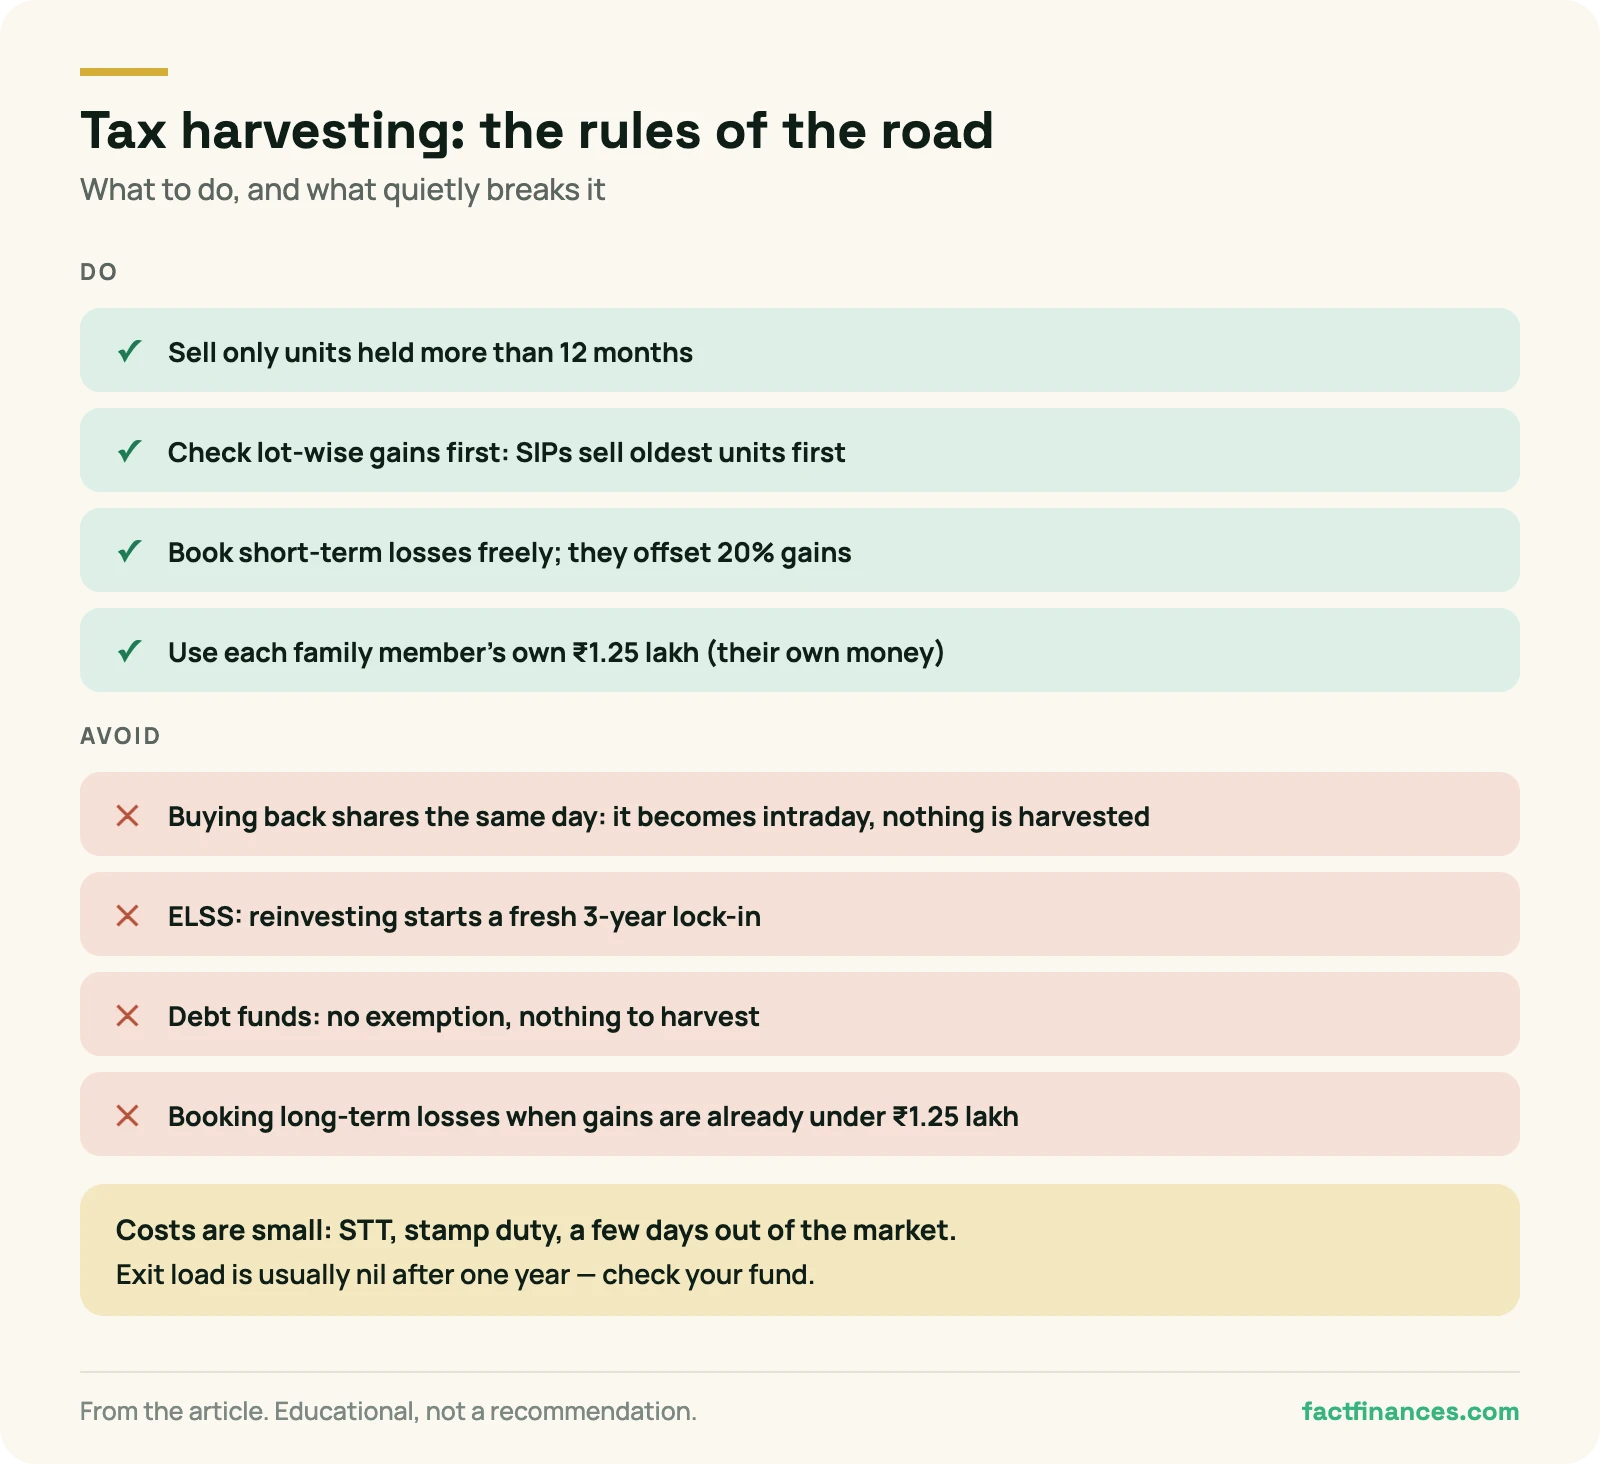
A sale and purchase of the same share on the same day nets off as an intraday trade: no delivery, no capital gain, and no reset of cost. Buy back the next trading day. With mutual funds this does not arise, because redemption and purchase are separate transactions with separate NAVs.
Costs and Catches
Costs and catches to check first
| Item | What to know |
|---|---|
| Exit load | Most equity funds charge 1% only within the first year; harvesting units older than a year usually costs nothing. Check your fund’s exit load period. |
| Transaction costs | STT of 0.1% on share sales (0.001% on fund redemptions), stamp duty of 0.005% on fund purchases, and brokerage on shares. Usually a few hundred rupees on ₹5 lakh. |
| Time out of the market | Fund redemptions take two to three working days to pay out. A sharp rally in those days is the main risk. |
| ELSS funds | Units are locked in for three years. Reinvesting in ELSS starts a fresh three-year lock-in. |
| Debt funds | No benefit. Debt funds bought from April 2023 are taxed at slab rate with no exemption. |
Switching between the direct and regular plan of a fund, or between funds, is also a sale. If you are moving to a direct plan anyway, do it inside the ₹1.25 lakh limit and you harvest at the same time.
Losses
Harvesting losses as well as gains
If some holdings are below cost, selling them books a capital loss that reduces this year’s taxable gains.
- A short-term loss can be set off against short-term gains (taxed at 20% on equity) or long-term gains. This is the most valuable loss to book.
- A long-term loss can only be set off against long-term gains.
- Losses not used this year carry forward for eight years, but only if you file your return by the due date.
Do not waste the exemption. Losses must be set off against gains before the ₹1.25 lakh exemption applies. If your long-term gains are already under ₹1.25 lakh, booking a long-term loss this year reduces gains that were tax-free anyway, and the loss is used up. Book long-term losses in a year your gains exceed the exemption.
India has no rule against buying back the same investment after selling at a loss, so you can book the loss and stay invested. Selling a fund or share only for tax is worth it only if you would be happy holding it again.
Family
Each family member has their own ₹1.25 lakh
The exemption is per person. Investments held in your spouse’s, parents’ or adult children’s own names each get ₹1.25 lakh a year, so a family of four can harvest up to ₹5 lakh of gains tax-free every year.
This works only for money that is genuinely theirs. If you give money to your spouse or a minor child and they invest it, the gains are added to your income under the clubbing rules and count against your own ₹1.25 lakh. Adult children investing their own earnings are not affected.
Reporting
Reporting harvested gains in your return
Every sale appears in your Annual Information Statement, so it must be in your return even though no tax is due. If your only capital gain is long-term equity gain within ₹1.25 lakh and you have no losses to carry forward, ITR-1 or ITR-4 can take it; otherwise use ITR-2, or ITR-3 if you have business income. See which ITR form to file.
To check the tax on a larger sale, use the capital gains tax calculator. If the sale takes your tax beyond TDS to ₹10,000 or more, advance tax may be due in the next instalment.
Common Mistakes
Mistakes people make with tax harvesting
1. Booking more than ₹1.25 lakh
Oldest-first selling in SIPs can book more gain than planned. Check lot-wise gains first.
2. Buying back shares the same day
It becomes an intraday trade and nothing is harvested. Buy back the next trading day.
3. Selling units held less than a year
That creates a short-term gain taxed at 20%, and often a 1% exit load.
4. Leaving it to 31 March
Fund redemptions placed on the last days may be processed in the next year. Do it by mid-March.
5. Forgetting to report the sale
Exempt gains still go in the return. A mismatch with the AIS brings a notice.
Talk It Through
Want to use this year’s ₹1.25 lakh before 31 March?
Send us your broker and CAMS/KFintech capital gains statements. We will work out how much gain is left to book, which lots to sell, whether booking losses helps, and help you file your ITR with the sales reported correctly. Ranchi, Deoghar and across India online.
Chat on WhatsApp Send a message · Capital gains tax calculator
Key takeaways
→ Long-term gains on listed shares and equity funds up to ₹1.25 lakh a year are tax-free; the exemption lapses if unused.
→ Harvesting books those gains and buys back, resetting your cost higher and saving up to ₹16,250 of future tax each year.
→ For FY 2026-27, sell by 31 March 2027, ideally by mid-March.
→ Sell only units held more than 12 months; buy back shares the next trading day, not the same day.
→ Book short-term losses freely; book long-term losses only when your gains exceed ₹1.25 lakh.
→ Each family member has their own ₹1.25 lakh, for money that is genuinely theirs.
Questions
Frequently asked questions
What is tax harvesting?
Selling shares or equity fund units held more than a year to book up to ₹1.25 lakh of tax-free long-term gain, then buying them back so your cost resets higher and your future taxable gain is lower.
How much tax does harvesting ₹1.25 lakh save?
Up to ₹15,625 at 12.5%, or ₹16,250 including 4% cess, for each year you use the exemption, realised when you eventually sell.
What is the last date for tax harvesting in FY 2026-27?
The sale must be in the financial year, so by 31 March 2027. Mutual fund redemptions take a few days, so do it by mid-March.
Can I buy the same shares back immediately?
Not on the same day: a same-day sale and purchase is treated as intraday and no gain is booked. Buy back on the next trading day. India has no wash-sale rule beyond that.
Does tax harvesting work for debt funds?
No. Debt funds bought from April 2023 are taxed at your slab rate however long you hold them, with no ₹1.25 lakh exemption.
Can my spouse harvest gains separately?
Yes, if the investments are in their name and bought with their own money. Each person has their own ₹1.25 lakh exemption.
Keep Learning
Next steps: Capital gains tax calculator · Capital gains tax on every asset · How mutual funds are taxed
The bigger picture: The complete guide to income tax in India · Advance tax: due dates and interest
About the author
Ujjwal Tiwary
ARN-144500 · NISM Series V-A certified since 2018 · Ranchi & Deoghar, Jharkhand
Ujjwal Tiwary is an AMFI-registered mutual fund distributor (ARN-144500) based in Ranchi and Deoghar, Jharkhand, and has held the NISM Series V-A certification since 2018. He works with families on mutual funds, insurance and income tax returns, and writes or personally reviews every article on FactFinances. He is not a SEBI-registered investment adviser; nothing on this site is personalised advice.
Disclaimer: FactFinances provides educational content only. This article is general information and is not tax, legal or financial advice. It is based on the Income-tax Act, 1961 (which still governs returns for FY 2025-26 and earlier) and the Income-tax Act, 2025 (in force from 1 April 2026), as understood at the time of writing. Tax law, due dates and their interpretation can change, and your tax depends on your full facts; check the current position on the Income Tax Department portal or consult a chartered accountant before acting. FactFinances offers ITR filing assistance; reading this article places you under no obligation to use it.